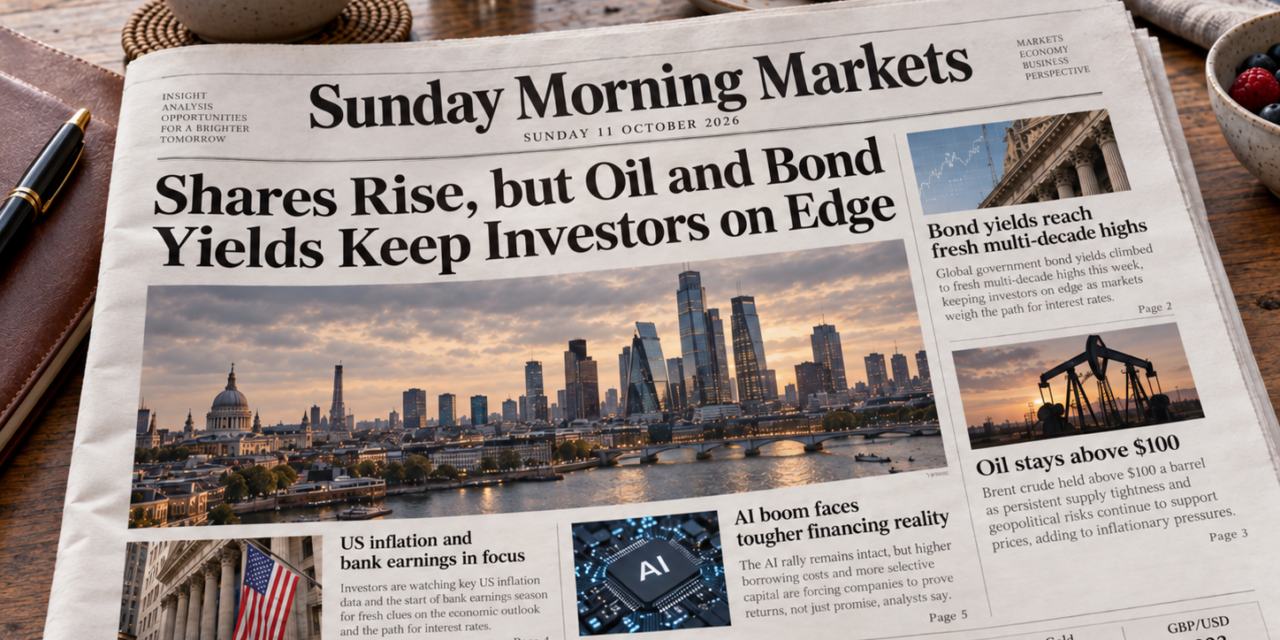
A similar story of equities up and yields up
It was a better week for shares than bonds. The S&P 500 gained 1.2% and approached its record high, while the FTSE 100 recovered from earlier losses. Y
et there were substantial movements within individual sectors. On Friday, T-Mobile fell more than 13%, while some telecommunications infrastructure companies rose sharply.
S&P 500
+1.2%
Last week
FTSE 100
+0.9%
Last week
US 10-year gilt
5.24%
Last week
Brent Crude
$104.72
Last week
The big picture
Shares remain resilient, but the cost of money is rising
Investors appear determined to look beyond the current inflation concerns. American shares finished higher, helped by expectations of another strong corporate earnings season. Analysts expect S&P 500 profits to grow by approximately 30% compared with last year.
Government bond markets remain considerably less comfortable.
US 10-year Treasury yields reached a 24-year high during the week, while oil remained above $100 a barrel. France’s government finances also attracted renewed scrutiny, contributing to higher European borrowing costs.
The question for investors is whether corporate earnings can continue growing quickly enough to offset increasingly expensive borrowing. This week’s US inflation report and the start of the major bank earnings season should provide some answers.
Last week: Three things that mattered
Government bond yields reached new highs
The US 10-year Treasury yield reached 5.36% on Wednesday, its highest level in more than 24 years, before retreating to around 5.24% by Friday.
In Europe, French 10-year yields approached 5%, reflecting concerns about the country’s budget deficit and next year’s presidential election.
Investors responded by directing approximately $154 billion into global money market funds, the largest weekly inflow since May.
Why markets reacted: Higher government borrowing requirements, persistent inflation and rising energy prices are forcing investors to demand more compensation for lending money over longer periods.
The Federal Reserve’s September meeting minutes provided some reassurance. Officials saw a further interest-rate increase as possible, but showed little appetite for a rapid succession of increases.
Why this matters: Higher bond yields increase mortgage and business borrowing costs. They also make government bonds more competitive with shares.
Investors holding long-duration bond funds face a particular risk: prices fall when market yields rise.
Oil stayed above $100 as supply concerns intensified
Brent crude ended Friday at $104.72 a barrel, up approximately 2.4% over the week.
Attacks affecting Middle Eastern shipping, fresh sanctions on Iranian exports and Hurricane Isaias in the Gulf of Mexico all contributed to supply concerns.
US energy producers temporarily shut down substantial production ahead of the hurricane. Meanwhile, President Trump indicated that the United States would not launch new attacks against Iran before November’s midterm elections.
Why markets reacted: Energy prices influence inflation expectations more quickly than many other economic variables.
Higher oil costs affect transport, manufacturing and eventually household spending. Airlines are already feeling the pressure; Delta reduced its earnings outlook, citing high fuel costs.
Why this matters: Oil remaining above $100 complicates the Federal Reserve’s efforts to bring inflation back towards 2%.
A sustained fall would provide welcome relief to bonds and sectors sensitive to consumer spending. Further increases would create another obstacle for central banks.
SpaceX sent telecommunications shares tumbling
One of Friday’s biggest market movements came from an unexpected direction.
SpaceX announced the acquisition of a nationwide portfolio of wireless spectrum licences, signalling plans to develop Starlink into a more substantial mobile telecommunications competitor.
Investors reacted dramatically.
T-Mobile shares fell 13.3%, AT&T declined 9.8% and Verizon lost 8.7%.
Meanwhile, mobile tower operators benefited, with Crown Castle gaining 15.6% and American Tower rising 9.3%.
Why this matters: Markets are trying to assess whether satellite technology could challenge established mobile networks.
SpaceX still faces considerable technical, regulatory and commercial obstacles. Nevertheless, share prices reflect future expectations, and those expectations can change before profits do.
It offers investors a useful reminder: companies considered defensive because of recurring revenues are not necessarily protected from technological competition.
This week: What investors should watch
1. Wednesday: US inflation
September’s Consumer Price Index is due on Wednesday 14 October at 1.30pm UK time.
Economists expect annual headline inflation of around 3.7%, compared with 3.4% in August.
The Federal Reserve meets again on 27–28 October, making this an important test of inflation expectations.
What could surprise markets?
A lower-than-expected reading could ease pressure on Treasury yields and support growth shares.
A stronger number would increase concerns about another rate increase, potentially supporting the dollar while putting pressure on bonds and highly valued equities.
Investors should pay particular attention to services inflation. This provides a better indication of whether price increases are spreading beyond energy.
2. Tuesday and Wednesday: US bank earnings
JPMorgan Chase, Goldman Sachs, Citigroup and Wells Fargo report on Tuesday. Bank of America and Morgan Stanley follow on Wednesday.
This is the first substantial test of third-quarter corporate profits.
Large US banks are expected to report healthy earnings growth, although banking shares have recently underperformed. Higher bond yields, funding costs and concerns about consumer credit have weighed on sentiment.
What investors should watch: The most useful information may come from management commentary on loan defaults, business borrowing and investment banking activity.
Strong earnings accompanied by improving loan demand would support confidence in the economy.
Rising bad-debt provisions or weaker lending would suggest higher borrowing costs are beginning to cause problems.
3. Thursday: UK economic growth
The ONS releases August GDP figures on Thursday 15 October at 7am.
The economy grew 0.4% in July, but the more important question is whether households and businesses are beginning to struggle with elevated borrowing and energy costs.
A stronger number could support UK shares exposed to domestic growth, although it might also strengthen expectations that the Bank of England will keep rates high.
Weaker activity could reduce gilt yields but raise concerns about company earnings.
Watch the service sector particularly closely, given its importance to the British economy.
4. Thursday: Another test for AI investment
Taiwan Semiconductor Manufacturing Company (TSMC) reports earnings on Thursday.
The company manufactures advanced chips for many of the world’s largest technology businesses, giving it a useful perspective on semiconductor demand.
Investors will focus on orders, manufacturing capacity and expectations for future AI-related spending.
Continued strong demand would support the wider semiconductor sector. Disappointing guidance could revive questions about whether investment in AI infrastructure is running ahead of commercial returns.
Investment Insight
A 5% bond yield doesn't mean a risk-free 5% annual return
Government bonds are offering income levels that investors haven’t seen for many years.
With UK 10-year gilts yielding around 5.4%, it is understandable that some investors are reassessing the balance between shares and bonds.
But there is an important distinction between yield and total return.
A newly purchased conventional gilt held until maturity offers a calculable return, assuming the government meets its obligations. Its market price before maturity can still fluctuate considerably.
When yields rise, existing bond prices fall. The longer the bond’s remaining maturity, generally the greater its sensitivity to interest-rate movements.
This is particularly relevant to investors holding gilt funds rather than individual gilts.
A gilt fund generally maintains a portfolio of bonds and doesn’t necessarily have a fixed maturity date. Investors therefore cannot assume they will recover their original investment simply by waiting.
US Treasuries introduce another consideration for UK investors: changes in the pound-dollar exchange rate can materially affect returns unless currency exposure is hedged.
The attraction of bonds has certainly increased. But selecting the appropriate maturity, understanding interest-rate sensitivity and deciding whether to hold individual bonds or funds remain important.
Five Things I'll Be Watching
-
US inflation: Wednesday’s CPI report could alter expectations for the Fed’s October decision.
-
10-year Treasury yield: A return towards 5.4% would put renewed pressure on borrowing costs and equity valuations.
-
US bank earnings: Commentary on lending and defaults should help establish whether higher rates are affecting the real economy.
-
Brent crude: Oil remaining above $100 continues to complicate the global inflation outlook.
-
TSMC earnings: Demand for advanced chips offers another test of the strength and durability of AI investment.
Final thought
Last week demonstrated that equity markets can remain resilient even when government bond yields are high and geopolitical risks remain unsettled.
Strong company profits provide support, but rising borrowing costs are making investors more selective.