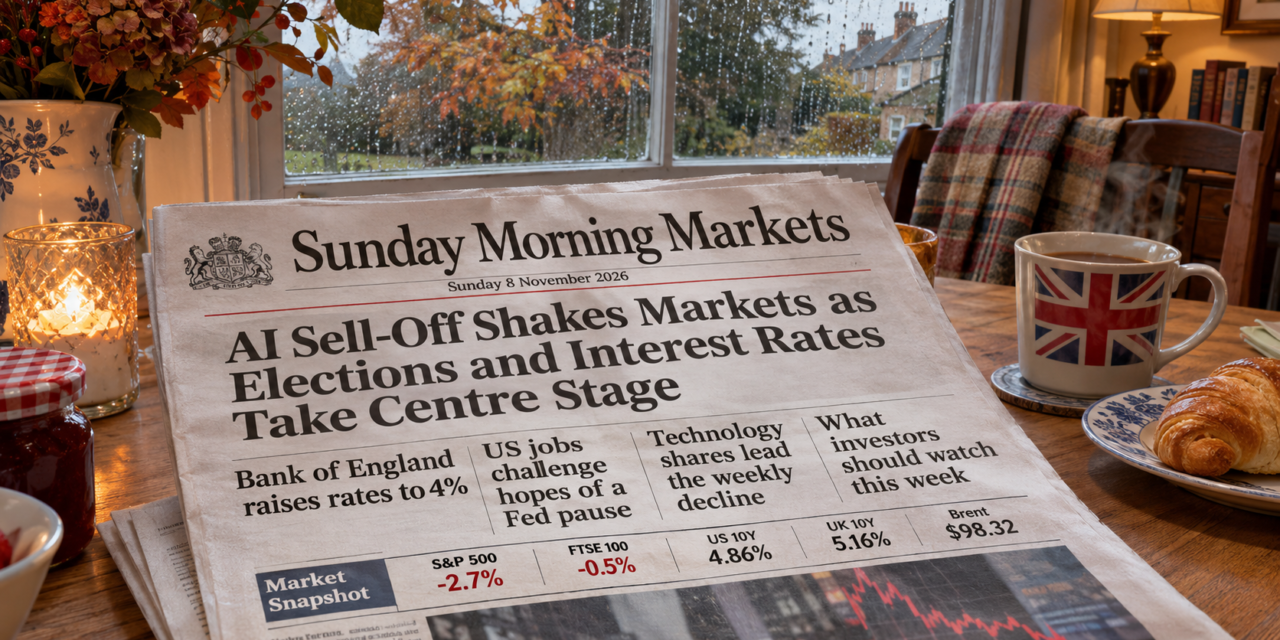
AI Sell-Off Shakes Markets as Elections and Interest Rates Take Centre Stage
November began with a sharp reversal in market sentiment. The S&P 500 lost 2.7%, while the technology-heavy Nasdaq fell 3.4%, its fourth consecutive weekly decline.
The sell-off was particularly severe in Asia. Japan’s Nikkei fell 9.3% and South Korea’s KOSPI lost 11.7% over the week. Meanwhile, oil fell more than 13%, taking Brent back below $100 a barrel.
Friday’s recovery in US technology shares offered some relief, but it wasn’t enough to reverse the week’s losses.
S&P 500
-2.7%
Last week
FTSE 100
-0.5%
Last week
US 10-year gilt
4.86%
Last week
Brent Crude
$98.32
Last week
The big picture
The AI boom faces a political and financial reality check
For much of 2026, artificial intelligence has driven global equity markets higher. Investors have accepted enormous spending on data centres and computer chips because they expect substantial future profits.
Last week, that confidence was tested.
The Democrats’ victory in the US midterm elections raised questions about future regulation of AI infrastructure. Technology shares fell sharply, with semiconductor companies experiencing their worst daily decline in more than six years.
Yet there was another important development: the Bank of England raised interest rates to 4%, while Friday’s stronger-than-expected US employment report increased expectations of another Federal Reserve rate rise in December.
Investors are now confronting an uncomfortable combination: expensive technology shares, uncertainty about future AI spending and interest rates that may remain higher for longer.
The central question is whether strong corporate earnings can justify valuations if the AI investment cycle begins to slow.
Last week: Three things that mattered
1. US elections triggered a sharp technology sell-off
What happened? Tuesday’s US midterm elections delivered major gains for the Democrats, who secured control of both the House of Representatives and Senate.
Markets initially welcomed the result, with US shares rallying on Wednesday as investors anticipated greater constraints on government spending.
That reaction reversed dramatically on Thursday.
The S&P 500 technology sector fell 7.3%, while the Philadelphia Semiconductor Index plunged more than 12%, its worst daily performance in over six years.
The Nasdaq entered correction territory, having fallen more than 10% from its October peak.
Why markets reacted. Investors became concerned that tighter regulation could delay AI data-centre construction, particularly following Democratic victories in states where substantial infrastructure investment is planned.
Environmental concerns, electricity demand and local opposition to new data centres featured prominently during the election campaign.
Why this matters. The market had assumed that AI infrastructure spending would continue expanding rapidly.
Any regulatory delays could affect chipmakers, data-centre operators, electricity suppliers and companies financing these projects.
Friday’s recovery, which included an 11% rise in AMD, suggests investors haven’t abandoned the AI growth story. But confidence is becoming more fragile.
The Bank of England raised rates and warned inflation could reach 5%
What happened? On Thursday, the Bank of England increased Bank Rate by 0.25 percentage points to 4%, its first increase in more than three years.
Eight members supported the rise, while Catherine Mann preferred a larger increase to 4.25%.
The Bank also delivered a concerning inflation forecast.
With UK inflation already at 3.5%, policymakers now expect it to approach 5% by the middle of 2027, largely because of higher energy costs.
Why markets reacted. Investors had expected the rate increase, but the Bank’s inflation outlook reinforced expectations of further tightening.
Governor Andrew Bailey indicated that another increase could become necessary if energy prices remain elevated.
The UK 10-year gilt yield finished around 5.16%, having benefited from a wider movement into government bonds during the technology sell-off.
Why this matters. For UK investors, higher interest rates affect mortgage costs, savings returns, company borrowing and gilt valuations.
The Bank faces a difficult choice: raise borrowing costs to prevent inflation becoming embedded, without weakening an economy already facing pressure from higher household energy bills.
Strong US jobs challenged hopes of an interest-rate pause
What happened? Friday’s US employment report surprised economists.
The economy created 165,000 jobs in October, compared with expectations of around 65,000.
Unemployment fell to 4.1%, while earlier employment figures were revised higher by a combined 84,000.
Average hourly earnings increased 0.4% during the month.
Why markets reacted. Stronger employment suggests the US economy remains resilient, reducing the need for the Federal Reserve to support growth through lower interest rates.
Markets increased the probability of a December rate rise to approximately 80%.
Treasury yields and the dollar rose following the announcement, while gold fell.
Why this matters. The Fed faces a different problem from investors worried about falling technology shares.
A strong labour market gives policymakers room to maintain restrictive interest rates while addressing inflation.
For equity investors, the question is whether company earnings can continue growing sufficiently to offset those higher financing costs.
This week: What investors should watch
1. Tuesday: US inflation could decide December’s Fed meeting
October’s Consumer Price Index arrives on Tuesday 10 November at 1.30pm UK time.
This is probably the week’s most important economic release.
Following Friday’s strong employment figures, markets already expect another rate increase in December.
What could surprise investors?
Lower-than-expected inflation would provide relief to government bonds and potentially support technology shares.
Higher inflation would reinforce expectations of further tightening, pushing Treasury yields and the dollar higher.
Investors should concentrate on core inflation, particularly services, to judge whether underlying price pressures are easing.
2. Thursday: How strong is the UK economy?
The ONS releases its first estimate of third-quarter UK GDP on Thursday 12 November at 7am, alongside September’s monthly growth figures.
The Bank of England has recently upgraded its assessment of economic activity, suggesting growth has proved stronger than expected.
A stronger GDP reading could reinforce expectations that interest rates need to remain elevated.
Weaker growth would increase concerns about the effect of higher energy prices and borrowing costs on households and businesses.
For UK investors, watch gilt yields and sterling closely.
The challenge is finding a balance between controlling inflation and maintaining economic growth.
3. Technology earnings provide another AI test
CoreWeave, Applied Materials and Cisco report this week.
These results matter particularly after the sharp technology sell-off.
CoreWeave provides specialised AI computing infrastructure, making its financing arrangements and investment plans especially relevant.
Applied Materials offers insight into semiconductor manufacturing demand, while Cisco provides evidence about spending on networking equipment.
Strong earnings and convincing forecasts could restore some confidence.
Further evidence of rising borrowing requirements, delayed projects or weaker customer demand could prolong the decline.
4. Friday: US producer-price inflation
Friday brings the October Producer Price Index.
This measures price changes received by businesses for their goods and services, providing another indication of inflation pressures within the economy.
A strong reading following Tuesday’s CPI report would reinforce concerns about persistent inflation.
Conversely, easing producer prices would suggest that some of the pressure on companies may be diminishing.
The figures could influence expectations for the Fed’s December meeting and the direction of government bond yields.
Investment Insight
Why market concentration matters when technology shares fall
Last week’s decline provides a useful reminder of the risks created by market concentration.
A relatively small number of large technology companies now account for a substantial proportion of the US equity market.
These businesses have delivered impressive earnings growth, but their success has also made global portfolios increasingly dependent on their performance.
This matters because investors holding a global index tracker may believe they are widely diversified across thousands of companies.
They are diversified by the number of holdings, but the largest companies still have a disproportionate influence on returns.
Consider a global fund where US equities represent around two-thirds of the portfolio. If the technology sector accounts for a substantial share of those US holdings, weakness in a handful of businesses can affect the entire fund.
That doesn’t mean investors should avoid US technology.
Many of these companies have strong balance sheets, substantial cash generation and established competitive advantages.
The issue is how much of a portfolio depends on one investment theme.
Diversification across regions, sectors and asset classes can reduce that dependence.
Last week’s contrasting performances illustrate the point. Japan and South Korea suffered heavy losses, while Indian equities recorded substantial gains.
For UK investors, this is a reason to review portfolio exposure rather than react to short-term market movements.
A diversified portfolio shouldn’t require every major technology company to deliver exceptional growth indefinitely.
Five Things I'll Be Watching
-
US inflation: Tuesday’s CPI could determine whether markets strengthen expectations of another Fed rate rise.
-
CoreWeave earnings: Investors want evidence that AI infrastructure spending can produce sustainable financial returns.
-
UK GDP: Thursday’s figures will test the Bank of England’s view that economic activity remains resilient.
-
10-year Treasury yield: A move back above 5% would increase pressure on equity valuations.
-
Market breadth: Whether the technology sell-off spreads into other sectors will indicate the strength of investor confidence.
Final Thought
Last week demonstrated how quickly market sentiment can change.
Technology companies that previously attracted considerable enthusiasm are now facing greater scrutiny over regulation, spending and future profitability.
Yet the underlying global economy remains reasonably resilient, with US employment growing faster than expected and corporate earnings continuing to provide support.
For long-term investors, the response shouldn’t be to abandon technology or attempt to predict the next market recovery.
It should be to ensure portfolios remain appropriately diversified, valuations are understood and investment decisions reflect long-term objectives.
Markets will continue to move between optimism and concern. Successful investing comes from maintaining discipline through both.