A positive week for equities, bonds yields slip again
Shares had a better week than the bond market. The S&P 500 gained 1.2% and the Nasdaq rose 2%, helped by renewed enthusiasm for artificial intelligence. The FTSE 100 also edged higher for a second consecutive week. Meanwhile, the US 10-year Treasury yield briefly reached 5.23%, its highest level since 2007, while bond-market volatility jumped sharply.
S&P 500
|+1.2%
Last week
FTSE 100
+0.3%
Last week
US 10-year gilt
5.16%
Last week
Brent Crude
$104.32
Last week
The big picture
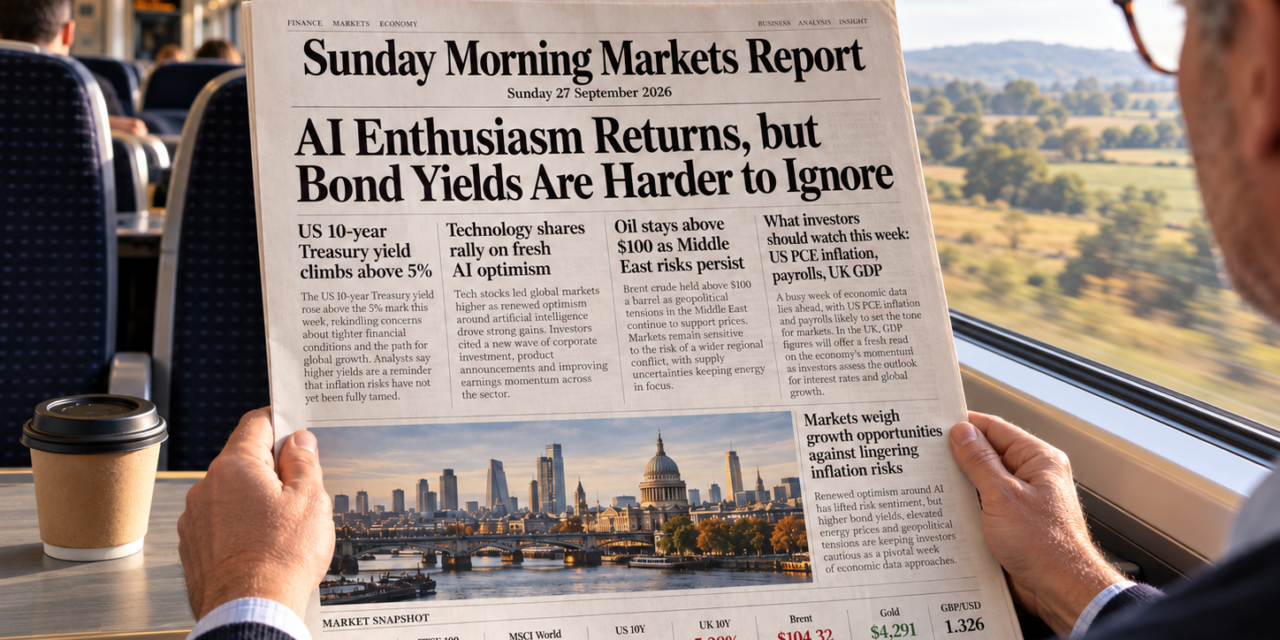
AI enthusiasm returns, but the bond market is becoming harder to ignore
Last week produced an unusual combination.
Technology shares rallied, helped by fresh AI developments from Microsoft, Meta and other companies. At the same time, government bond yields surged as investors priced in a greater chance of further interest-rate rises.
That tension now sits at the centre of markets.
The S&P 500 is trading at just under 19 times expected earnings, according to LSEG data, while a 10-year US Treasury offers a yield above 5%. Investors therefore have a genuine choice between taking equity risk and earning a substantial return from government bonds. Reuters
This week brings two tests of that balance: US inflation on Wednesday and the September employment report on Friday.
Last week: Three things that mattered
Bond yields pushed into territory not seen for almost two decades
The US 10-year Treasury yield reached 5.2297% on Friday before easing back to around 5.16%. The 30-year yield climbed as high as 5.53%, its highest since 2004. Bond-market volatility also rose by roughly 30% over the week. Reuters
The cause is familiar: persistent inflation, high energy prices and growing expectations that the Federal Reserve may have to raise rates again.
Markets now put the chance of an October Fed increase at roughly 66%, up sharply during the week. Reuters
For investors, this is more than a fixed-income story. A higher Treasury yield changes the price investors are prepared to pay for shares, property and credit. It also raises refinancing costs for businesses.
The longer yields remain above 5%, the more pressure there is on companies to justify expensive valuations with stronger profits.
AI optimism came back quickly
Monday set the tone for technology shares.
The Nasdaq reached a record close as semiconductor stocks surged. AMD rose around 10%, briefly taking its market value above $1 trillion, while Intel and Arm also posted large gains. Reuters
Later in the week, Microsoft added 3.7% after announcing new Copilot features, including coding tools and an always-on AI agent. Meta gained strongly over the week following the launch of its Muse AI agent. Reuters
That helped the S&P 500 gain 1.2% despite the rise in bond yields.
The lesson is becoming clearer. Investors still believe AI can deliver substantial productivity and earnings growth, but the sector is now having to offset a much higher cost of capital.
That is a tougher test than it was when bond yields were closer to 3% or 4%.
Oil eased, but the Middle East risk did not disappear
Brent crude fell about 2% on Friday to $104.32 a barrel as hopes grew that the US and Iran could agree a phased path towards reopening the Strait of Hormuz. Investing.com South Africa
That was enough to give bond markets some relief, but oil remains above $100 and supply risks persist.
Negotiators are discussing a framework in which Iran would reopen the Strait while the US relaxed parts of its economic blockade. At the same time, attacks on Saudi infrastructure continue to worry energy markets. Reuters
Why does this matter?
Because oil is still one of the main links between geopolitics and monetary policy. If crude falls meaningfully, inflation expectations may soften and bond yields could ease. If talks fail and oil rises again, central banks may have even less room to pause.
This week: What investors should watch
1. Wednesday: the Federal Reserve’s preferred inflation measure
The US Bureau of Economic Analysis publishes August PCE inflation on Wednesday, alongside personal income, spending and the final estimate of second-quarter GDP. Bureau of Economic Analysis
PCE matters because it is the inflation measure the Federal Reserve watches most closely.
A softer reading would challenge the market’s growing conviction that another rate rise is coming and could push Treasury yields lower.
A stronger number would reinforce the opposite view: that inflation is proving more persistent and rates may need to rise again.
With the 10-year yield already above 5%, even a modest surprise could produce a large market reaction.
2. Friday: the US jobs report
September’s employment report arrives on Friday 2 October. Bureau of Labor Statistics
Reuters expects payroll growth of around 100,000 jobs. Reuters
A stronger report would suggest the US economy continues to absorb higher interest rates without much damage. That is good for earnings, but it could also strengthen the case for another Fed increase.
A weak report could pull bond yields lower, though investors would then have to consider whether growth is slowing too quickly.
The most market-friendly outcome may again be somewhere in the middle: slower employment growth without a sharp deterioration in unemployment.
3. Tuesday: US job openings
The latest JOLTS report on job vacancies is due on Tuesday. Bureau of Labor Statistics
This receives less attention than payrolls but still matters because it offers a different view of labour demand.
If vacancies remain elevated, the Fed may conclude that wage pressure can persist. A clear fall would suggest employers are becoming less willing to hire, giving the central bank more reason to wait.
Given how sensitive bond markets have become, even second-tier labour data can now move rate expectations.
4. Wednesday: a check on the UK economy
The ONS publishes the final estimate of UK second-quarter GDP on Wednesday, together with the balance of payments and household-sector data. Office for National Statistics
The headline GDP figure is unlikely to change dramatically, but the detail matters.
Investors will want to know whether household spending and business investment look strong enough to withstand gilt yields above 5%. Any large revision could influence expectations for the Bank of England.
For UK investors, sterling and gilt yields may respond more sharply than the FTSE 100.
Investment Insight
What does a 5% bond yield change?
Central banks can’t produce more oil, repair a pipeline or reopen a shipping route. So why would the Bank of England or Federal Reserve respond to an energy shock by raising interest rates?
Their concern is what happens next. A temporary energy shock can then develop into persistent domestic inflation.
It is the second-round effects which are the concern and what we should be watching.
The Bank of England says there is little evidence of material second-round effects in the UK so far. But it also says the risk increases the longer energy prices stay high.
That explains why the Bank can leave rates unchanged today while warning that it may have to raise them later.
For investors, it is also why oil, wage growth and bond yields need to be viewed together. One month’s inflation figure tells only part of the story. What matters is whether higher prices start changing behaviour across the economy.
Five Things I'll Be Watching
- US PCE inflation – Wednesday’s figure could either calm or intensify expectations for another Fed rate rise.
- US payrolls – Friday will show whether the labour market is still strong enough to withstand tighter monetary policy.
- 10-year Treasury yield – A sustained move above 5.25% would increase the pressure on equity valuations.
- Brent crude – Progress on a US-Iran agreement could matter as much to bonds as another economic release.
- UK gilt yields – A 10-year yield around 5.4% remains a significant constraint on borrowing and growth.
Final thought
Last week showed that strong equity markets and rising bond yields can coexist, at least for a while.
AI optimism was powerful enough to lift shares even as government borrowing costs climbed to levels unseen for years.
That balance may not last indefinitely.
The more income available from government bonds, the more selective investors are likely to become about the price they pay for shares. That is no bad thing.
Whilst Government Bonds might not be in favour at the moment, if you can build a plan to hold these to maturity they provide a good level of return, with minimal risk. You can’t say the same for equities.